
Figuring out how to pay off student loans faster can save you thousands of dollars in interest and years off your repayment timeline. Whether you have federal loans, private loans, or a mix of both, this guide covers 9 proven strategies to accelerate your payoff — without requiring a massive salary or winning the lottery.
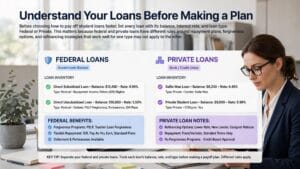
Understand Your Loans Before Making a Plan
Before choosing how to pay off student loans faster, list every loan you have with its balance, interest rate, and loan type (federal or private). This matters because federal and private loans have different rules around repayment plans, forgiveness options, and refinancing — strategies that work well for one type may not apply to the other.
Strategy 1: Make Extra Payments Toward Principal
Any payment beyond your required minimum should be directed specifically toward your loan’s principal balance, not just applied to future payments. Many loan servicers apply extra payments to future installments by default unless you specifically request otherwise — always confirm this with your servicer, since applying extra money to principal is what actually accelerates payoff and reduces total interest.
Strategy 2: Target the Highest-Interest Loan First
If you have multiple student loans, focusing extra payments on the loan with the highest interest rate first — while making minimum payments on the rest — minimizes the total interest you’ll pay over time. This mirrors the debt avalanche method covered in our guide on debt snowball vs avalanche, which also explains an alternative approach if you’re more motivated by paying off smaller balances first.
Strategy 3: Make Biweekly Payments Instead of Monthly
Splitting your monthly payment in half and paying every two weeks results in 26 half-payments per year — equivalent to 13 full monthly payments instead of 12. This single change can shave months or years off your repayment timeline without feeling like a major budget adjustment, since the extra payment builds up gradually rather than all at once.
Strategy 4: Apply Windfalls Directly to Your Loans
Tax refunds, work bonuses, and cash gifts are ideal candidates for extra student loan payments because they weren’t part of your regular budget to begin with — directing them entirely toward your loan balance won’t affect your day-to-day finances at all.
Strategy 5: Consider Refinancing (With Caution)
Refinancing replaces your existing loans with a new loan, ideally at a lower interest rate, which can meaningfully speed up how to pay off student loans faster by reducing the interest portion of every payment. However, refinancing federal loans into a private loan means permanently losing access to federal protections like income-driven repayment plans and loan forgiveness programs — so this strategy generally makes more sense for private loans or for federal loan borrowers who are confident they won’t need those protections.
Strategy 6: Explore Employer Student Loan Assistance
A growing number of employers now offer student loan repayment assistance as a workplace benefit, contributing directly toward employee loan balances. If this isn’t offered at your workplace, it may be worth asking your HR department, as this benefit has become increasingly common and cost-effective for employers to provide.
Strategy 7: Automate Payments for a Rate Discount
Many loan servicers offer a small interest rate reduction — often around 0.25% — for enrolling in automatic payments. While modest on its own, this discount compounds over the life of the loan and requires no ongoing effort once set up.
Strategy 8: Increase Income Specifically for Loan Payoff
Dedicating a side income stream entirely to student loan payments can dramatically accelerate your timeline. Even a modest side hustle generating a few hundred extra dollars a month, directed entirely at your loans, can cut years off a typical 10-year repayment plan. Our guide on 21 side hustle ideas covers realistic ways to generate this extra income.
Strategy 9: Avoid Lifestyle Inflation While Paying Off Loans
As your income grows through raises or promotions, directing that additional income toward loan payoff — rather than proportionally increasing spending — accelerates your timeline significantly faster than sticking to a fixed payment amount for years while your income rises around it.
Should You Pay Off Student Loans or Invest First?
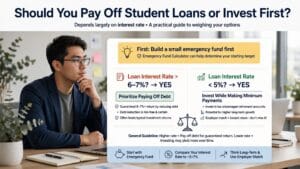
This depends largely on your interest rate. As a general guideline:
- If your loan interest rate is above 6-7%: Prioritizing payoff often makes more mathematical sense, since guaranteed debt reduction at that rate is difficult to consistently beat through investing.
- If your loan interest rate is below 5%: Investing while making minimum loan payments may produce better long-term results, particularly in tax-advantaged retirement accounts with an employer match.
Regardless of which path you choose, make sure you have a small emergency fund first — our Emergency Fund Calculator can help you determine a starting target so an unexpected expense doesn’t force you into new debt while paying off existing loans.
Understanding Federal Loan Forgiveness Programs
If you work in public service, nonprofit, or certain qualifying fields, federal loan forgiveness programs may eliminate your remaining balance after a set number of qualifying payments. These programs have specific eligibility requirements and paperwork obligations, so it’s worth reviewing official details through the U.S. Department of Education’s Federal Student Aid site rather than relying on secondhand information, since program rules can change.
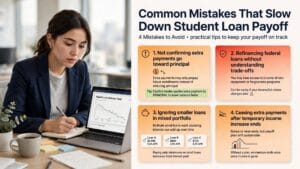
Common Mistakes That Slow Down Student Loan Payoff
- Not confirming extra payments go toward principal. Without specifying this, extra payments may simply prepay future installments instead of reducing your balance faster.
- Refinancing federal loans without understanding the trade-offs. Losing access to income-driven repayment or forgiveness programs can be a costly mistake if your circumstances change later.
- Ignoring smaller loans in a mixed portfolio. Multiple small loans can add up to significant total interest if left on minimum payments indefinitely.
- Ceasing extra payments after a temporary income increase ends. Building payoff momentum around a temporary bonus or raise without a sustainable plan can stall progress once that extra income disappears.
A Realistic Example
Consider a $30,000 student loan at 6% interest on a standard 10-year repayment plan. The standard monthly payment would be roughly $333. Adding just $100 extra per month toward principal could cut approximately 2-3 years off the repayment timeline and save several thousand dollars in total interest — illustrating how relatively modest extra payments compound into significant results over time.

Final Thoughts
There’s no single strategy for how to pay off student loans faster that works for everyone — the right combination depends on your interest rates, loan types, and overall financial picture. Start with the strategies that require no extra money (confirming principal payments, automating for a rate discount) before moving to strategies that require additional income or refinancing decisions.
Every extra dollar directed toward your loans today saves multiple dollars in future interest — making student loan payoff one of the more mathematically rewarding financial moves available to most borrowers. Ready to plan your payoff timeline? Try our free Debt Payoff Calculator and see exactly how extra payments could accelerate your progress.