Debt Consolidation vs Balance Transfer: Which Is Better?

If you are carrying high-interest credit card debt, you have probably wondered about debt consolidation vs balance transfer. Both promise to lower your interest and simplify your payments, and both can save real money when used well. But they work in very different ways, and picking the wrong one can leave you paying more than you expected.

In this guide you will learn how each option works, how the debt consolidation vs balance transfer choice compares on fees, interest, credit impact, and payoff time, and which situations favor one over the other. You will also see a simple example with real numbers so the trade-offs are easy to understand.

What Is a Balance Transfer?

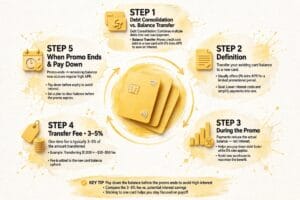
A balance transfer means moving debt from one or more credit cards onto a new credit card, usually one that offers a low or 0% introductory interest rate for a limited time. During that promotional period, more of every payment goes toward the actual balance instead of interest, which can help you pay the debt off faster.

Most balance transfer cards charge a transfer fee, often a percentage of the amount you move. When the promotional period ends, any remaining balance starts to accrue interest at the card’s regular rate, which can be high. That is why the plan only works if you can pay the balance down before the offer expires. Knowing how a balance transfer works is the first step in the debt consolidation vs balance transfer decision.
debt consolidation vs balance transfer comparison with calculator and credit cards

What Is a Debt Consolidation Loan?

A debt consolidation loan is a personal loan you use to pay off several debts at once. Instead of making many payments to different lenders, you make one monthly payment to the new lender. Most consolidation loans have a fixed interest rate and a fixed term, so you know exactly what you will pay each month and when you will be debt free.

Some lenders charge an origination fee, which is usually a percentage of the loan amount and is often taken out of the money you receive. Your interest rate depends mainly on your credit profile and income, so borrowers with stronger credit tend to get better rates. Now that you understand both products, the debt consolidation vs balance transfer comparison becomes much clearer.

Debt Consolidation vs Balance Transfer: Key Differences at a Glance

Here is a quick side-by-side view of the debt consolidation vs balance transfer comparison:

Feature Balance Transfer Card Debt Consolidation Loan
Type of product Credit card Personal loan
Interest rate Low or 0% for a limited time, then a higher regular rate Fixed rate for the full loan term
Upfront fee Balance transfer fee Possible origination fee
Payment Flexible, but you set your own payoff plan Fixed monthly payment
Best for Smaller balances you can repay within the promo period Larger balances that need more time
Main risk Interest returns when the promo ends Fees and a longer repayment period

This table gives you the overview, but the details behind each row decide which option saves you more. Let’s go through them.

Debt Consolidation vs Balance Transfer: Interest Rates and Costs

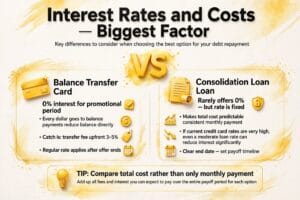
Interest is the biggest factor in the debt consolidation vs balance transfer decision. A balance transfer card can offer 0% interest for a promotional period, which means every dollar you pay goes to the balance. The catch is the transfer fee, which you pay upfront, and the regular rate that applies after the offer ends.

A consolidation loan rarely offers 0%, but the rate is fixed. That makes your total cost predictable. If your current credit card rates are very high, even a moderate loan rate can reduce your interest significantly, and you get a clear end date for your debt.

To compare them fairly, look at the total cost rather than only the monthly payment. Add up all fees and the interest you expect to pay over the entire payoff period for each option.
debt consolidation vs balance transfer comparison with calculator and credit cards

Debt Consolidation vs Balance Transfer: A Simple Example

Let’s say you owe $6,000 on a credit card with a 24% interest rate. These numbers are illustrative and rounded, but they show how the debt consolidation vs balance transfer choice can play out:

Option Monthly Payment Time to Pay Off Approx. Interest and Fees
Keep the card at 24% and pay $343 per month $343 About 22 months About $1,457 in interest
Balance transfer (3% fee, 0% for 18 months) $343 18 months $180 fee, no interest if paid in time
Consolidation loan (12% rate, 36 months, no origination fee) $199 36 months About $1,174 in interest

In this debt consolidation vs balance transfer example, the balance transfer is the cheapest option, but only because the payment of $343 per month is high enough to clear the balance before the 0% period ends. The loan costs more in total interest but has a much lower monthly payment, which can matter if your budget is tight. Your real numbers will differ, so test your own balances in our free Debt Payoff Calculator.

Debt Consolidation vs Balance Transfer: Credit Score Impact

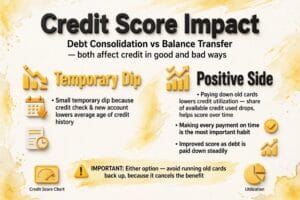
In the debt consolidation vs balance transfer comparison, both options affect your credit, in both good and bad ways. Applying for a new card or loan usually causes a small, temporary dip because of the credit check. A new account can also lower the average age of your credit history.

On the positive side, paying down your old cards lowers your credit utilization, which is the share of your available credit you are using, and that can help your score over time. Making every payment on time is the most important habit with either option. Just avoid running the old cards back up, because that cancels the benefit.
debt consolidation vs balance transfer comparison with calculator and credit cards

When a Balance Transfer Makes More Sense

In the debt consolidation vs balance transfer debate, a balance transfer tends to win in these situations:

  • Your balance is small enough to pay off within the promotional period.
  • You have good credit and expect to qualify for a 0% offer.
  • You can commit to a fixed monthly payment that clears the balance on time.
  • You will stop using the old cards for new purchases.

When a Debt Consolidation Loan Makes More Sense

A consolidation loan usually wins the debt consolidation vs balance transfer comparison in these situations:

  • Your balance is large and you need several years to repay it.
  • You want one fixed payment and a clear payoff date.
  • You are worried about a promotional rate expiring before you finish.
  • You are consolidating several types of debt, not only credit cards.

Risks to Watch Out For

No matter which side of the debt consolidation vs balance transfer choice you pick, a few risks apply to both:

  • Running up the old cards again. If the paid-off cards fill up again, you end up with more debt than before.
  • Missing a payment. A late payment can cancel a promotional rate or trigger fees.
  • Ignoring the end of the promo period. Set a reminder a few months before a balance transfer offer ends.
  • Paying only the minimum. On a balance transfer card, minimum payments may not clear the balance in time.
  • Stretching the loan too long. A very long term lowers the monthly payment but raises total interest.

Other Options to Consider

The debt consolidation vs balance transfer question is not the only way out. If neither option fits your situation, consider these alternatives:

  • Debt snowball or avalanche. Pay off debts in a planned order without opening new accounts. Our guide to debt snowball vs debt avalanche compares both.
  • Nonprofit credit counseling. A certified counselor can review your budget and may offer a debt management plan. The National Foundation for Credit Counseling is one place to find help.
  • Calling your lender. Ask about a lower rate or a hardship program. It costs nothing to ask.

Be careful with companies that promise to erase your debt fast or charge large upfront fees. The Federal Trade Commission and the Consumer Financial Protection Bureau publish free guides on spotting debt relief scams.

How to Choose Between Debt Consolidation and a Balance Transfer

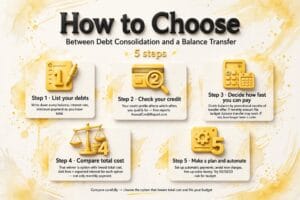
If you are still unsure about the debt consolidation vs balance transfer choice, follow these steps:
debt consolidation vs balance transfer comparison with calculator and credit cards

Step 1: List your debts. Write down every balance, interest rate, and minimum payment so you know your total.

Step 2: Check your credit. Your credit profile affects which offers you qualify for. You can request free reports at AnnualCreditReport.com.

Step 3: Decide how fast you can pay. Divide your balance by the promotional months of a transfer offer. If that monthly amount fits your budget, a balance transfer may work. If it does not, a loan with a longer term may be safer.

Step 4: Compare the total cost. The true winner of the debt consolidation vs balance transfer choice is the option with the lowest total cost for you. Add fees and expected interest for each option, not only the monthly payment.

Step 5: Make a plan and automate. Set up automatic payments and avoid new charges. To free up extra money for debt, try the 50/30/20 rule for your budget.

Common Mistakes in the Debt Consolidation vs Balance Transfer Decision

  • Choosing by the monthly payment only. A low payment can hide a higher total cost.
  • Forgetting the fees. Transfer fees and origination fees reduce your savings.
  • Not having a payoff plan. A 0% offer is only useful if you know how you will clear the balance in time.
  • Treating consolidation as a cure. It lowers interest, but it does not fix overspending. Review your budget too.
  • Skipping an emergency fund. Without savings, a surprise bill can push you back onto credit cards. See our guide to building an emergency fund.

Frequently Asked Questions About Debt Consolidation vs Balance Transfer

What is the difference between debt consolidation vs balance transfer?

A balance transfer moves credit card debt onto a new card, often with a 0% introductory rate. Debt consolidation uses a personal loan to pay off debts and replaces them with one fixed payment.

Is debt consolidation vs balance transfer better for large balances?

Usually a consolidation loan fits large balances better because it gives you a longer, fixed repayment period. Balance transfer promotions are time limited, so they suit balances you can clear quickly.

Does a balance transfer hurt your credit score?

It can cause a small, temporary dip because of the credit check and the new account. Paying down your balances and making on-time payments can help your score over time.

Can I get a balance transfer with bad credit?

The best 0% offers usually go to borrowers with good credit. If your credit is lower, you may qualify for a loan or card with a less attractive rate, or you may want to try credit counseling instead.

Which saves more money in the debt consolidation vs balance transfer comparison?

It depends on your balance, your payment, and the rates you qualify for. A balance transfer can cost less if you pay off the balance during the promotional period, while a loan can cost less than a card at a high rate if you need more time.

Should I consolidate debt or use the snowball method?

It depends on your credit and your habits. Consolidation can lower your interest, while the snowball method builds motivation with quick wins. Some people combine both approaches.

Final Thoughts

The debt consolidation vs balance transfer decision comes down to two questions: how much you owe and how quickly you can pay it. A balance transfer can be the cheapest path for smaller balances you can clear during the promotional period, while a consolidation loan offers a steady plan for larger debts. Whichever you choose, the real win comes from making every payment on time and avoiding new debt.

Ready to see your own numbers? Use our free Debt Payoff Calculator to estimate your payoff date, and read our complete guide on how to get out of debt for the full step-by-step plan.

This article is for educational purposes only and is not financial advice. Rates, fees, and terms vary by lender and by borrower. Consider speaking with a qualified professional about your specific situation.
How to Get Out of Debt: Step-by-Step Plan (2026)

If you are searching for how to get out of debt, you have already done the hardest part: you are facing the problem instead of ignoring it. Debt can feel heavy, but it responds to a clear plan. In this guide you will learn how to get out of debt step by step, from listing what you owe to choosing a payoff method, lowering your interest, and making sure the debt does not come back.

Whether you are dealing with credit card debt, a personal loan, a car loan, or a mix of everything, the process of how to get out of debt is the same. You need to see the full picture, free up extra money, attack your balances in a smart order, and build habits that protect you afterward. Let’s walk through it together.

How to Get Out of Debt: The 8-Step Plan at a Glance

  1. List every debt you owe
  2. Build a budget that finds extra money
  3. Start a small emergency fund
  4. Choose a debt payoff method
  5. Lower your interest costs
  6. Increase your income
  7. Automate and track your progress
  8. Stop adding new debt

Why Getting Out of Debt Feels So Hard

Understanding how to get out of debt starts with understanding why debt is hard to escape. Interest works against you every single month, so a large part of each payment can go to the lender instead of to your balance. Minimum payments are often set low, which keeps the balance alive for years. On top of that, debt brings stress, and stress makes it harder to plan calmly. The good news is that a written plan removes much of that pressure, because you always know what to do next.

Step 1: List Every Debt You Owe

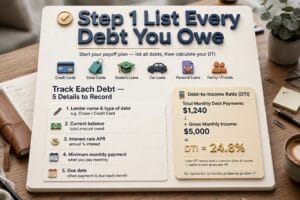
The first step in how to get out of debt is knowing exactly what you are up against. Many people avoid this because it feels uncomfortable, but a debt payoff plan cannot work without real numbers. Write down every debt in a spreadsheet or notebook, including credit cards, store cards, student loans, car loans, personal loans, and any money you owe to family or friends.

For each debt, record these details:

  • Lender name and type of debt
  • Current balance
  • Interest rate (APR)
  • Minimum monthly payment
  • Due date

If you are not sure about a balance or an account you forgot about, you can request your free credit reports from AnnualCreditReport.com, the official site for free reports in the United States. Reviewing them helps you catch every open account.

Not all debt is equally urgent. High-interest debt such as credit cards and payday loans usually deserves attention first, while lower-interest debt such as a mortgage or some student loans can often be handled with regular payments. Sorting your list this way makes the rest of the plan much clearer.

Once you have the list, add up your total monthly debt payments and divide that number by your gross monthly income. This gives you your debt-to-income ratio (DTI). A lower DTI means debt takes up a smaller share of your income, and it is a useful number to track as you pay off debt over time.

Person reviewing a debt payoff plan with a calculator and notebook

Step 2: Build a Budget That Finds Extra Money

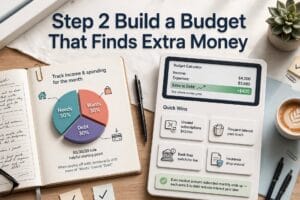
A budget is the engine of any plan for how to get out of debt, because you cannot pay off debt faster without extra cash flow. Track your income and spending for a month, then separate your expenses into needs, wants, and debt payments. Popular frameworks like the 50/30/20 rule can be a helpful starting point, but when you are working on a debt payoff plan you may temporarily shift more of the “wants” portion toward debt.

Look for quick wins: unused subscriptions, frequent takeout, bank fees, or insurance you have not shopped around for in years. Even a modest amount redirected every month adds up, because every extra dollar sent to debt reduces the interest you pay later. You can use our free Budget Calculator to see where your money goes and how much you can realistically put toward debt each month.

Person reviewing a debt payoff plan with a calculator and notebook

Step 3: Start a Small Emergency Fund First

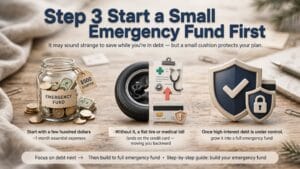
It may sound strange to save while you are in debt, but a small cushion protects your plan for how to get out of debt. Without one, a flat tire or a medical bill goes straight onto a credit card, and you end up moving backward. Many people start with a small starter fund, such as a few hundred dollars or roughly one month of essential expenses, and then focus on debt.

Once your high-interest balances are under control, you can grow that cushion into a full emergency fund. Our guide to building an emergency fund explains how to do it step by step.

Person reviewing a debt payoff plan with a calculator and notebook

Step 4: Choose a Debt Payoff Method

This is the heart of how to get out of debt faster. Two popular strategies work well, and the best one is the one you will actually stick with.

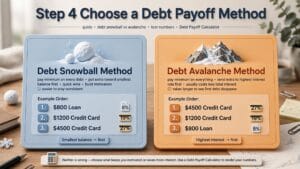
The Debt Snowball Method

With the snowball method, you pay the minimum on every debt and put all extra money toward the smallest balance first. When it is gone, you roll that payment into the next smallest balance. The quick wins build motivation, which is why many people find it easier to stay consistent.

The Debt Avalanche Method

With the avalanche method, you pay the minimum on everything and send extra money to the debt with the highest interest rate first. This usually costs less in total interest, but it can take longer to see the first debt disappear.

A Simple Example

Imagine three debts (illustrative numbers only): a $800 loan at 8%, a $1,200 credit card at 19%, and a $4,500 credit card at 27%. The snowball order would be the $800 loan, then the $1,200 card, then the $4,500 card. The avalanche order would be the 27% card, then the 19% card, then the 8% loan. Neither is wrong. If you want to compare both approaches in detail, read our guide on debt snowball vs debt avalanche, or test your own numbers in the Debt Payoff Calculator.

Person reviewing a debt payoff plan with a calculator and notebook

Step 5: Lower Your Interest Costs

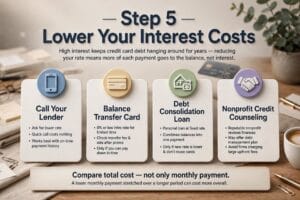
If you want to know how to get out of debt faster, lowering your interest rate is one of the most powerful moves. High interest is what keeps credit card debt hanging around for years, and reducing your rate means more of each payment goes to the balance instead of to interest. Here are the main options to consider:

  • Call your lender and ask for a lower rate. It does not always work, but a short phone call costs nothing, especially if you have a history of on-time payments.
  • Balance transfer card. Some cards offer a low or 0% introductory rate for a limited time. Check the transfer fee and the rate after the promotional period ends, and only use this if you can realistically pay the balance down in time.
  • Debt consolidation loan. A personal loan with a fixed rate can replace several high-interest balances with one payment. It only helps if the new rate is lower and you do not run the cards back up.
  • Nonprofit credit counseling. A reputable nonprofit agency can review your finances and may offer a debt management plan. The National Foundation for Credit Counseling is one place to find certified counselors.

Be cautious with companies that promise to erase your debt quickly or charge large upfront fees. The Consumer Financial Protection Bureau publishes free guides on debt, credit, and how to spot debt relief scams. Whichever option you choose, compare the total cost, not only the monthly payment. A lower monthly payment stretched over a longer period can cost more overall.

Person reviewing a debt payoff plan with a calculator and notebook

Step 6: Increase Your Income

Cutting expenses has a limit, but income can grow, and this is often what separates a slow plan from a fast one when you are working out how to get out of debt on any income. Even a small side income dedicated entirely to debt can speed up your debt payoff plan. Options include freelancing, selling items you no longer use, taking extra shifts, doing seasonal work, or asking for a raise if you have taken on more responsibility. Treat this extra income as a debt-only fund so it does not get absorbed into everyday spending.

Step 7: Automate and Track Your Progress

Consistency matters most when you are learning how to get out of debt. Set up automatic payments for at least the minimums so you never miss a due date, and schedule your extra payment right after payday. Then track your progress monthly: total debt, number of debts left, and your debt-to-income ratio. Seeing the total fall is a powerful motivator. Many people mark each paid-off debt on a chart or checklist to celebrate the milestone.

Step 8: Stop Adding New Debt

A payoff plan only works if you stop borrowing while you pay. Consider pausing new credit card spending, using cash or a debit card for everyday purchases, and waiting 24 to 48 hours before non-essential purchases. If you rely on credit for emergencies, that is another reason a starter emergency fund matters. Over time, building a habit of saving for planned expenses, such as with a sinking fund, helps you avoid borrowing for predictable costs.

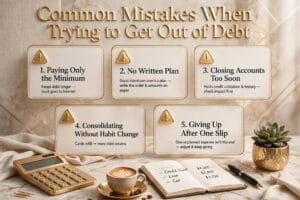
Common Mistakes When Learning How to Get Out of Debt

  • Paying only the minimum. Minimum payments are designed to keep you in debt longer, and most of the payment can go toward interest.
  • Not having a written plan. Good intentions are not a debt payoff plan. Put the order and amounts on paper.
  • Closing accounts without thinking. Closing old cards can affect your credit utilization and credit history, so check the impact first.
  • Using consolidation without changing habits. If the cards fill up again, you end up with more debt than before.
  • Giving up after a slip. One unplanned expense does not ruin the plan. Adjust and keep going.

Person reviewing a debt payoff plan with a calculator and notebook

How to Get Out of Debt on a Low Income

Many people assume that how to get out of debt is only a question for high earners, but a low income does not make it impossible. It usually means the timeline is longer and every decision matters more. Start with a bare-bones budget that covers essentials only, then look for one realistic way to add income, even a few extra hours a month. Ask lenders about hardship programs or lower rates, and consider nonprofit credit counseling for free guidance. Small, steady extra payments work better than big plans you cannot keep up, because the goal is progress you can repeat every month.

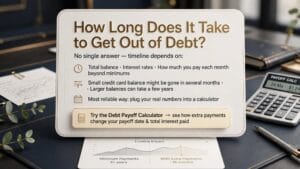
How Long Does It Take to Get Out of Debt?

There is no single answer, because the timeline depends on your total balance, your interest rates, and how much you can pay each month beyond the minimums. A small credit card balance might be gone in several months, while larger balances can take a few years. The most reliable way to estimate your own date is to plug your real numbers into a calculator. Try our Debt Payoff Calculator to see how extra payments change your payoff date and the total interest you pay.

how to get out of debt step by step plan with calculator and notebook

Frequently Asked Questions About Getting Out of Debt

What is the first step in how to get out of debt?

The first step is to list every debt with its balance, interest rate, and minimum payment. You cannot build a payoff plan until you can see the full picture in one place.

What is the fastest way to get out of debt?

The fastest approach is usually to combine a tight budget, extra income, and a focused payoff method. Sending every spare dollar to one target debt while paying minimums on the rest, and lowering your interest where possible, shortens the timeline the most.

Should I pay off debt or save money first?

For most people, a balanced approach works best: build a small starter emergency fund first so surprise costs do not become new debt, then focus on paying off high-interest debt, then grow your savings.

Is debt snowball or avalanche better?

Avalanche usually saves more on interest, while snowball can provide faster motivation. The better method is the one you can follow consistently until the debt is gone.

How do I get out of credit card debt?

List each card with its balance and APR, stop adding new charges, choose snowball or avalanche, and consider lowering your interest through a rate negotiation, balance transfer, or consolidation loan if it fits your situation.

Can I get out of debt on a low income?

Yes, although it may take longer. Focus on the essentials: a bare-bones budget, one small extra income source, interest reduction where possible, and steady progress. Even small, consistent extra payments make a real difference over time.

Final Thoughts

Knowing how to get out of debt is not about a secret trick. It is about seeing your numbers clearly, creating room in your budget, choosing a payoff method, and staying consistent until the last balance is gone. Start with Step 1 today: list your debts and total them. Then use the Debt Payoff Calculator to turn your plan into a real timeline.

This article is for educational purposes only and is not financial advice. Consider speaking with a qualified professional about your specific situation.
How to Pay Off Student Loans Faster: 9 Proven Strategies

Figuring out how to pay off student loans faster can save you thousands of dollars in interest and years off your repayment timeline. Whether you have federal loans, private loans, or a mix of both, this guide covers 9 proven strategies to accelerate your payoff — without requiring a massive salary or winning the lottery.

Understand Your Loans Before Making a Plan

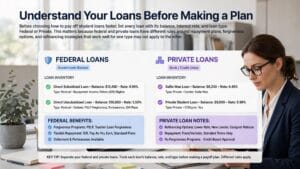
Before choosing how to pay off student loans faster, list every loan you have with its balance, interest rate, and loan type (federal or private). This matters because federal and private loans have different rules around repayment plans, forgiveness options, and refinancing — strategies that work well for one type may not apply to the other.

how to pay off student loans faster strategies

Strategy 1: Make Extra Payments Toward Principal

Any payment beyond your required minimum should be directed specifically toward your loan’s principal balance, not just applied to future payments. Many loan servicers apply extra payments to future installments by default unless you specifically request otherwise — always confirm this with your servicer, since applying extra money to principal is what actually accelerates payoff and reduces total interest.

Strategy 2: Target the Highest-Interest Loan First

If you have multiple student loans, focusing extra payments on the loan with the highest interest rate first — while making minimum payments on the rest — minimizes the total interest you’ll pay over time. This mirrors the debt avalanche method covered in our guide on debt snowball vs avalanche, which also explains an alternative approach if you’re more motivated by paying off smaller balances first.

Strategy 3: Make Biweekly Payments Instead of Monthly

Splitting your monthly payment in half and paying every two weeks results in 26 half-payments per year — equivalent to 13 full monthly payments instead of 12. This single change can shave months or years off your repayment timeline without feeling like a major budget adjustment, since the extra payment builds up gradually rather than all at once.

Strategy 4: Apply Windfalls Directly to Your Loans

Tax refunds, work bonuses, and cash gifts are ideal candidates for extra student loan payments because they weren’t part of your regular budget to begin with — directing them entirely toward your loan balance won’t affect your day-to-day finances at all.

Strategy 5: Consider Refinancing (With Caution)

Refinancing replaces your existing loans with a new loan, ideally at a lower interest rate, which can meaningfully speed up how to pay off student loans faster by reducing the interest portion of every payment. However, refinancing federal loans into a private loan means permanently losing access to federal protections like income-driven repayment plans and loan forgiveness programs — so this strategy generally makes more sense for private loans or for federal loan borrowers who are confident they won’t need those protections.

Strategy 6: Explore Employer Student Loan Assistance

A growing number of employers now offer student loan repayment assistance as a workplace benefit, contributing directly toward employee loan balances. If this isn’t offered at your workplace, it may be worth asking your HR department, as this benefit has become increasingly common and cost-effective for employers to provide.

Strategy 7: Automate Payments for a Rate Discount

Many loan servicers offer a small interest rate reduction — often around 0.25% — for enrolling in automatic payments. While modest on its own, this discount compounds over the life of the loan and requires no ongoing effort once set up.

Strategy 8: Increase Income Specifically for Loan Payoff

Dedicating a side income stream entirely to student loan payments can dramatically accelerate your timeline. Even a modest side hustle generating a few hundred extra dollars a month, directed entirely at your loans, can cut years off a typical 10-year repayment plan. Our guide on 21 side hustle ideas covers realistic ways to generate this extra income.

Strategy 9: Avoid Lifestyle Inflation While Paying Off Loans

As your income grows through raises or promotions, directing that additional income toward loan payoff — rather than proportionally increasing spending — accelerates your timeline significantly faster than sticking to a fixed payment amount for years while your income rises around it.

Should You Pay Off Student Loans or Invest First?

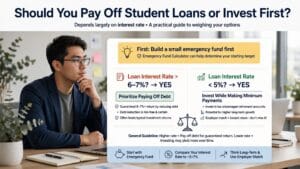
This depends largely on your interest rate. As a general guideline:

  • If your loan interest rate is above 6-7%: Prioritizing payoff often makes more mathematical sense, since guaranteed debt reduction at that rate is difficult to consistently beat through investing.
  • If your loan interest rate is below 5%: Investing while making minimum loan payments may produce better long-term results, particularly in tax-advantaged retirement accounts with an employer match.

Regardless of which path you choose, make sure you have a small emergency fund first — our Emergency Fund Calculator can help you determine a starting target so an unexpected expense doesn’t force you into new debt while paying off existing loans.

how to pay off student loans faster strategies

Understanding Federal Loan Forgiveness Programs

If you work in public service, nonprofit, or certain qualifying fields, federal loan forgiveness programs may eliminate your remaining balance after a set number of qualifying payments. These programs have specific eligibility requirements and paperwork obligations, so it’s worth reviewing official details through the U.S. Department of Education’s Federal Student Aid site rather than relying on secondhand information, since program rules can change.

Common Mistakes That Slow Down Student Loan Payoff

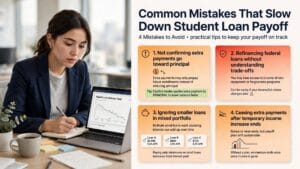
  • Not confirming extra payments go toward principal. Without specifying this, extra payments may simply prepay future installments instead of reducing your balance faster.
  • Refinancing federal loans without understanding the trade-offs. Losing access to income-driven repayment or forgiveness programs can be a costly mistake if your circumstances change later.
  • Ignoring smaller loans in a mixed portfolio. Multiple small loans can add up to significant total interest if left on minimum payments indefinitely.
  • Ceasing extra payments after a temporary income increase ends. Building payoff momentum around a temporary bonus or raise without a sustainable plan can stall progress once that extra income disappears.

how to pay off student loans faster strategies

A Realistic Example

Consider a $30,000 student loan at 6% interest on a standard 10-year repayment plan. The standard monthly payment would be roughly $333. Adding just $100 extra per month toward principal could cut approximately 2-3 years off the repayment timeline and save several thousand dollars in total interest — illustrating how relatively modest extra payments compound into significant results over time.

how to pay off student loans faster strategies

Final Thoughts

There’s no single strategy for how to pay off student loans faster that works for everyone — the right combination depends on your interest rates, loan types, and overall financial picture. Start with the strategies that require no extra money (confirming principal payments, automating for a rate discount) before moving to strategies that require additional income or refinancing decisions.

Every extra dollar directed toward your loans today saves multiple dollars in future interest — making student loan payoff one of the more mathematically rewarding financial moves available to most borrowers. Ready to plan your payoff timeline? Try our free Debt Payoff Calculator and see exactly how extra payments could accelerate your progress.

7 Proven Ways to Pay Off Debt Faster: Snowball vs Avalanche

When it comes to paying off debt, the debt snowball vs avalanche debate is one of the most common questions people face once they decide to get serious about becoming debt-free. Both methods work — thousands of people have paid off debt using each one — but they work in very different ways, and picking the wrong one for your personality can mean giving up before you finish.

This guide breaks down exactly how each method works, compares the real math behind debt snowball vs avalanche, and helps you decide which approach fits how you actually think about money.

What Is the Debt Snowball Method?

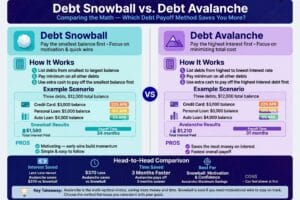
The debt snowball method, popularized by financial expert Dave Ramsey, focuses on psychology over math. Here’s how it works:

  1. List all your debts from smallest balance to largest, ignoring interest rates.
  2. Make minimum payments on everything except the smallest debt.
  3. Throw every extra dollar you can at that smallest debt until it’s paid off.
  4. Once it’s gone, roll that entire payment amount into the next-smallest debt.
  5. Repeat until every debt is paid off.

debt snowball vs avalanche method comparison

The core idea behind the debt snowball is momentum. Paying off a full debt — even a small one — creates a quick win that builds motivation to keep going, which is often more valuable than saving a few extra dollars in interest.

What Is the Debt Avalanche Method?

The debt avalanche method takes the opposite approach, prioritizing interest rate over balance size:

  1. List all your debts from highest interest rate to lowest, ignoring the balance.
  2. Make minimum payments on everything except the highest-interest debt.
  3. Put every extra dollar toward that highest-interest debt until it’s gone.
  4. Move to the next-highest interest rate debt and repeat.

debt snowball vs avalanche method comparison

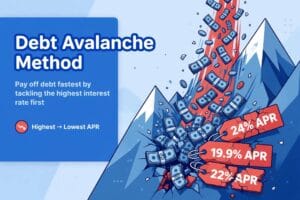
Mathematically, the debt avalanche method is more efficient — you pay less total interest over the life of your debt payoff journey because you’re eliminating your most expensive debt first.

Debt Snowball vs Avalanche: The Real Math

To understand the practical difference in the debt snowball vs avalanche debate, let’s look at an example. Imagine three debts:

  • Credit Card A: $1,500 balance at 24% interest
  • Credit Card B: $4,000 balance at 19% interest
  • Personal Loan: $8,000 balance at 12% interest

With the snowball method, you’d pay off Credit Card A first (smallest balance), then Credit Card B, then the Personal Loan — even though Credit Card A doesn’t have the highest interest rate.

debt snowball vs avalanche method comparison

With the avalanche method, you’d pay off Credit Card A first too — in this case, it happens to have both the smallest balance and the highest interest rate. But if Credit Card A had a lower interest rate than Credit Card B, avalanche would tell you to attack Credit Card B first instead, saving more in interest even though its balance is larger.

In cases where your smallest-balance debt and your highest-interest debt aren’t the same account, avalanche will almost always save you more money in total interest paid — sometimes by hundreds or even thousands of dollars depending on your balances and rates.

Want to see exactly how fast you could be debt-free with your specific numbers? Try our free Debt Payoff Calculator to compare timelines side by side.

Debt Snowball vs Avalanche: Pros and Cons

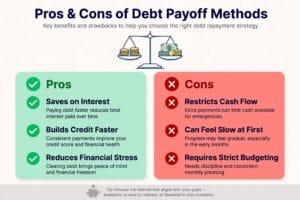
Debt Snowball: Pros

  • Fast early wins build motivation and momentum
  • Simpler to stay consistent with, especially for beginners
  • Reduces the number of monthly payments you’re juggling sooner

Debt Snowball: Cons

  • You may pay more in total interest over time
  • High-interest debt keeps accumulating charges while you focus on smaller balances

debt snowball vs avalanche method comparison

Debt Avalanche: Pros

  • Saves the most money in total interest paid
  • Mathematically the most efficient path to debt freedom
  • Often results in a faster overall payoff timeline

Debt Avalanche: Cons

  • Can feel slow and discouraging if your highest-interest debt also has a large balance
  • Requires more discipline since early “wins” may take longer to achieve

Which Method Should You Choose?

The honest answer in the debt snowball vs avalanche debate is: the best method is the one you’ll actually stick with. A mathematically perfect plan you abandon after two months is worse than a slightly less efficient plan you follow through to completion.

debt snowball vs avalanche method comparison

Choose the Snowball Method If:

  • You’ve struggled to stay motivated with past debt payoff attempts
  • You need quick wins to stay engaged with the process
  • Your debts don’t vary dramatically in interest rate

Choose the Avalanche Method If:

  • You’re motivated by numbers and long-term savings, not quick wins
  • One or more of your debts has a significantly higher interest rate than the others
  • You’re disciplined enough to stay consistent without frequent milestones

A Hybrid Approach: The Best of Both Worlds

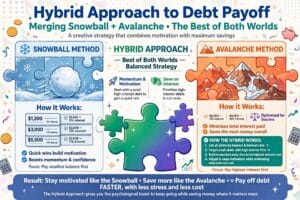
You don’t have to choose strictly one method. Some people start with the snowball method to build early momentum by knocking out one or two small debts, then switch to the avalanche method once they’ve built the habit of consistently paying extra toward debt. This hybrid approach captures the psychological benefit of the snowball’s quick wins while still prioritizing high-interest debt sooner rather than later.

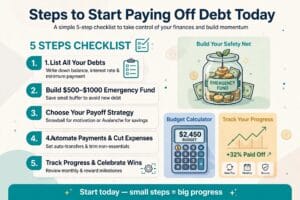
Steps to Start Paying Off Debt Today, Regardless of Method

debt snowball vs avalanche method comparison

1. List Every Debt You Have

Write down every debt — balance, minimum payment, and interest rate — in one place. You can’t apply either the debt snowball or avalanche method without a full, honest picture.

2. Build a Small Emergency Fund First

Before aggressively paying down debt, most financial experts recommend having at least $500-$1,000 set aside. Without this buffer, a single unexpected expense often becomes new debt on a credit card, undoing your progress. Our Emergency Fund Calculator can help you determine a starting target.

3. Free Up Extra Payment Money

Review your budget for anywhere you can redirect money toward debt payoff — even $50-$100 extra per month accelerates either method significantly. Our Budget Calculator can help identify where that extra money might come from.

4. Automate Minimum Payments

Set up automatic minimum payments on all debts so you never miss one, which protects your credit score. Then manually direct any extra payment toward your target debt each month based on your chosen method.

5. Track Your Progress Visually

Whether it’s a simple spreadsheet, an app, or a printed debt payoff chart, seeing your progress — however you’re measuring it — reinforces the habit and keeps you moving forward during the months when progress feels slow.

Common Mistakes in Both Methods

  • Taking on new debt while paying off old debt. This undoes progress from either method and is one of the most common reasons debt payoff plans fail.
  • Not adjusting the plan as your situation changes. A raise, a new expense, or a bonus should be factored back into your payoff strategy.
  • Ignoring high-interest debt for too long with the snowball method. If your highest-interest debt also has a large balance, consider switching toward avalanche sooner rather than later.
  • Underestimating how much interest compounds. According to the Consumer Financial Protection Bureau, minimum payments alone can keep you in debt for decades on high-interest balances.

Final Thoughts

debt snowball vs avalanche method comparison

The debt snowball vs avalanche decision ultimately comes down to knowing yourself. If you need momentum and quick wins to stay motivated, the snowball method will likely get you further than a mathematically perfect plan you abandon out of frustration. If you’re driven by efficiency and want to minimize total interest paid, the avalanche method is the smarter long-term choice.

Whichever method you choose, the most important factor is consistency — extra payments applied month after month, regardless of which debt they’re targeting first. Ready to map out your own payoff timeline? Try our free Debt Payoff Calculator and see exactly how fast you could be debt-free.