Learning how to retire early has become one of the most searched financial goals in recent years, largely thanks to the FIRE movement — Financial Independence, Retire Early. While retiring in your 30s or 40s sounds extreme, the underlying principles are straightforward and achievable for many people with the right plan. This guide covers 8 practical steps to help you build a realistic path toward early retirement.
What Does “Retiring Early” Actually Mean?
Retiring early doesn’t necessarily mean never working again. For most people pursuing this goal, it means reaching financial independence — having enough invested assets that your investment income can cover your living expenses without relying on a traditional paycheck. Some people fully stop working at that point; others shift to part-time work, consulting, or passion projects because they no longer need the income to survive.
Step 1: Calculate Your FIRE Number
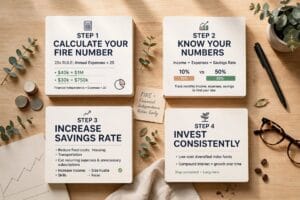
The most common formula for figuring out how much you need is based on the 25x rule: multiply your expected annual expenses by 25. This comes from the idea that withdrawing 4% of your portfolio annually is historically sustainable over a long retirement.
FIRE Number = Annual Expenses × 25
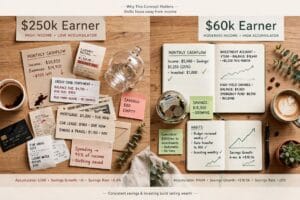
For example, if you spend $40,000 a year, your target would be $1,000,000. If you can live on $30,000 a year, your target drops to $750,000. This single calculation is often the biggest wake-up call for people exploring how to retire early — the number depends far more on spending than on income.
Step 2: Know Your Numbers — Income, Expenses, and Savings Rate
Your savings rate — the percentage of income you save and invest — is the single biggest lever in this entire plan. Someone saving 10% of their income might work 40+ years before reaching financial independence. Someone saving 50% or more can often reach the same goal in 15-17 years, because they are simultaneously reducing their required expenses and increasing their invested assets. Our free Budget Calculator can help you find your actual savings rate today.
Step 3: Increase Your Savings Rate Aggressively
This is where the math gets genuinely exciting. Small increases in your savings rate produce disproportionately large reductions in the years until financial independence, because you’re improving both sides of the equation at once — spending less and investing more. Two practical levers:
- Reduce fixed expenses — housing and transportation are usually the largest categories, so changes here have outsized impact
- Increase income — through raises, side income, or career changes, directing all of the increase toward savings
Step 4: Invest Consistently in Low-Cost, Diversified Assets
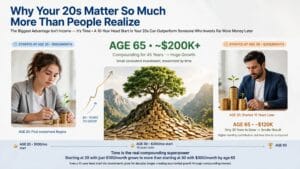
Most people pursuing early retirement rely heavily on broad, low-cost index funds rather than trying to pick individual winning stocks. Our guide on index funds for beginners covers exactly how to get started, and understanding how compound interest works explains why starting as early as possible matters so much for this specific goal.
Step 5: Eliminate High-Interest Debt First
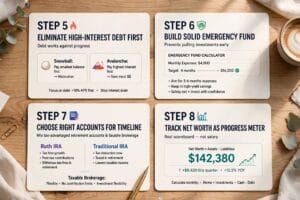
Carrying high-interest debt while pursuing early retirement works directly against your progress, since the interest you’re paying typically exceeds what you’d realistically earn investing that same money. Our comparison of debt snowball vs avalanche can help you choose the fastest path to becoming debt-free.
Step 6: Build a Solid Emergency Fund
Without adequate emergency savings, an unexpected expense can force you to pull from investments early or take on new debt — both of which set back your timeline. Use our free Emergency Fund Calculator to determine a target before ramping up aggressive investing.
Step 7: Choose the Right Accounts for Your Timeline
Retirement accounts offer tax advantages but often come with restrictions on accessing funds before a certain age. If early retirement is your goal, you’ll likely need a mix of tax-advantaged retirement accounts and a taxable brokerage account for the years before you can access retirement funds penalty-free. Our comparison of Roth IRA vs traditional IRA explains the tax tradeoffs of each option.
Step 8: Track Your Net Worth as Your Progress Meter
Your net worth — not your salary — is the real scoreboard for this goal. See our guide on how to calculate your net worth and use our free Net Worth Tracker to monitor your progress toward your FIRE number over time.
Different Flavors of Early Retirement
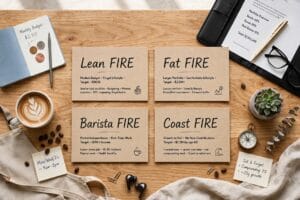
Not everyone pursuing early retirement wants the exact same lifestyle. A few common variations:
- Lean FIRE: Retiring on a modest budget, often requiring a smaller invested total but a more frugal lifestyle
- Fat FIRE: Retiring with a larger portfolio to support a more comfortable, less restrictive lifestyle
- Barista FIRE: Reaching partial financial independence and working part-time or in a lower-stress job to cover remaining gaps
- Coast FIRE: Having enough invested that it will grow to your full number by traditional retirement age without further contributions, allowing you to reduce work intensity sooner
How Long Will It Actually Take?
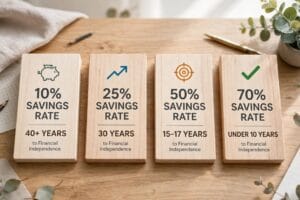
The relationship between savings rate and years to financial independence follows a fairly predictable pattern, assuming consistent investment returns:
- 10% savings rate: Roughly 40+ years
- 25% savings rate: Roughly 30 years
- 50% savings rate: Roughly 15-17 years
- 70%+ savings rate: Under 10 years in many cases
Want to see this play out with your own numbers? Our free Investment Growth Calculator can help visualize how different contribution levels compound over your specific timeline.
Common Mistakes When Pursuing Early Retirement
- Underestimating healthcare costs. Before eligibility for government health programs, healthcare can be one of the largest expenses for early retirees to plan around.
- Not accounting for inflation. A FIRE number calculated today needs to keep growing with inflation, not stay fixed.
- Ignoring sequence of returns risk. Retiring right before a market downturn can affect a portfolio differently than the same downturn happening mid-career, so many early retirees build in extra buffer for this.
- Being too rigid about the exact number. Some flexibility — working part-time occasionally, adjusting spending in down years — can significantly reduce the strictness required to reach the goal.
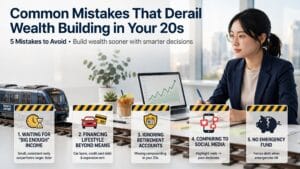
- Sacrificing too much along the way. Extreme frugality that damages quality of life for a decade isn’t sustainable for everyone, and burnout can derail the entire plan.
Is Early Retirement Realistic for Everyone?
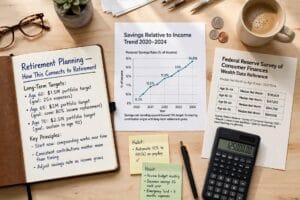
Not every income level makes traditional FIRE timelines realistic, and that’s okay. The underlying principles — track spending, increase savings rate, invest consistently, avoid high-interest debt — improve financial security at any pace, even if full early retirement in 15 years isn’t the specific outcome. For many people, simply moving from a 10% savings rate to a 20% or 25% savings rate meaningfully improves both current financial stability and future flexibility.
The U.S. Securities and Exchange Commission’s Investor.gov offers additional resources on the long-term power of consistent investing, which underlies every version of this strategy.

Final Thoughts
Figuring out how to retire early comes down to a few core moves repeated consistently over years: calculate your number, increase your savings rate, invest in low-cost diversified assets, and eliminate the debt and emergency gaps that could derail your progress. There’s no single formula that guarantees a specific age, but the math rewards anyone willing to save aggressively and stay invested for the long term.
Ready to calculate your own path? Try our free Investment Growth Calculator and see how your current savings rate translates into a realistic timeline toward financial independence.
This article is for educational purposes only and is not personal financial advice.