How to Invest $100: A Simple Beginner’s Guide (2026)

If you are wondering how to invest $100, the good news is that you can start today. You do not need thousands of dollars or a financial advisor. With a free or low-cost brokerage account, fractional shares, and a diversified fund, $100 is enough to become an investor and start building a habit that can grow over many years.

In this guide you will learn how to invest $100 step by step, which options beginners often use, what to check before you start, and what $100 could grow into over time. All growth examples are hypothetical, and investing always involves risk, so you will also see what can go wrong.

Is $100 Enough? How to Invest $100 as a Beginner

Yes. Many brokers now let you open an account with no minimum, and many allow fractional shares, which means you can buy a small slice of a fund or stock instead of a whole share. That makes $100 a practical starting amount, and it makes learning how to invest $100 a realistic goal.

It is important to be realistic, though. A single $100 investment will not make you rich. The real power comes from repeating it every month, because the habit matters more than the first deposit. If you want a broader overview, read our guide on how to start investing with little money.
how to invest $100 as a beginner with a phone and growing savings

Before You Start: A Checklist for How to Invest $100

Investing makes the most sense when your basics are covered. Before you invest, check these three things:

  • High-interest debt. If you carry credit card debt at a high rate, paying it down often beats investing, because the interest you avoid can be larger than what you might earn. See our plan on how to get out of debt.
  • A small cushion. Keep emergency savings so you never have to sell investments at a bad time. Our guide to sinking fund vs emergency fund explains how to separate your savings.
  • Money you will not need soon. Money for bills in the next few years is usually better kept out of the stock market, because prices can fall.

If your employer offers a retirement plan match, that is often worth capturing before anything else, because it is extra money added to your account.

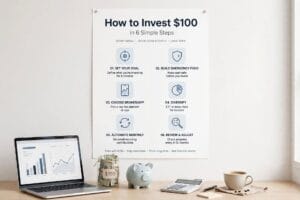
How to Invest $100 in 6 Simple Steps

Follow these six steps in order. Most people can finish them in less than an hour.

Step 1: Decide What the Money Is For

Your goal decides how to invest $100 and where the money should go. Retirement and other goals more than five years away can handle the ups and downs of the market. Goals that are closer, such as a vacation next year, are usually better suited to savings.

Step 2: Choose an Account Type

The account you open affects taxes and access to your money. The most common options for beginners are:

  • A taxable brokerage account. Flexible, and you can withdraw anytime, but gains may be taxed.
  • A retirement account such as an IRA. Offers tax advantages, but has rules about contributions and withdrawals.

If you are not sure which fits you, check the rules for each type or speak with a qualified tax professional.

Step 3: Open the Account

Choose a well-known, regulated broker, then complete the online application. You will need to confirm your identity, and you can usually link a bank account to transfer money. You can check the background of a broker with FINRA.

Step 4: Pick a Diversified Investment

Knowing how to invest $100 wisely starts with diversification. For a first $100, most beginners choose a broad index fund or ETF. These hold hundreds or thousands of companies, so your money is spread out instead of resting on one business. If you are not sure whether to choose an ETF or a mutual fund, read our comparison of ETF vs mutual fund.

Step 5: Place Your Order

Transfer your $100, search for the fund, and enter the dollar amount if your broker supports fractional shares. Review the order carefully before you confirm. If you are buying a whole share instead, check that the share price fits within $100.

Step 6: Automate and Repeat

Set up an automatic monthly investment, even if it is the same $100. This approach is called dollar-cost averaging, and our guide to dollar-cost averaging explains how it works and why many beginners like it.
how to invest $100 as a beginner with a phone and growing savings

How to Invest $100: Options Compared

Here are the most common places beginners use when they learn how to invest $100:

Option How It Works Good For Main Consideration
Index ETF A basket of many investments that trades like a stock Low-cost diversification You place the orders yourself
Index mutual fund A pooled fund priced once per day Automatic monthly investing Some funds have minimums
Fractional shares A small slice of a single company Owning a piece of a company you know Concentrated in one business
Robo-advisor An automated service that builds a portfolio for you Hands-off investing Check the management fee
Savings account Earns interest, not invested in markets Short-term goals Interest rates change

For long-term goals, a diversified index fund is a common starting point because it keeps costs low and spreads risk. Whatever you choose, make sure you understand what you are buying.

What Could $100 Grow Into?

Here is a hypothetical example, assuming an average return of 7% a year. This return is only an assumption for illustration, real returns vary every year, and your investments can lose value:

Years One-Time $100 $100 a Month Total You Contribute Monthly
10 years About $197 About $17,300 $12,000
20 years About $387 About $52,100 $24,000
30 years About $761 About $122,000 $36,000

The lesson is clear: a one-time $100 grows slowly, but $100 invested every month can grow into a meaningful amount because your earnings start earning too. You can test your own numbers in our free Investment Growth Calculator.

How Fees Affect a $100 Investment

When you think about how to invest $100, costs matter even on small amounts, because they come out of your returns every year. The main cost is the expense ratio, an annual percentage charged by a fund. On a $100 balance, a 0.05% expense ratio costs about five cents a year, while a 1% expense ratio costs about one dollar a year. That difference seems tiny now, but it grows as your balance grows.

Also check whether your broker charges trading commissions or account fees. Many brokers offer commission-free trading for common funds, but you should always confirm before you invest.

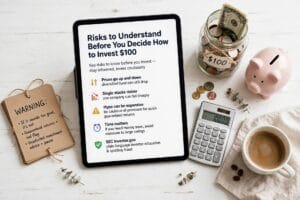
Risks to Understand Before You Decide How to Invest $100

All investing involves risk, including the possible loss of money. Keep these points in mind:

  • Prices go up and down. A diversified fund can still drop in value during a downturn.
  • Single stocks are riskier. One company can fall sharply, which is why diversified funds are popular with beginners.
  • Hype can be expensive. Be cautious with anyone promising quick or guaranteed returns.
  • Time matters. Money you may need soon should not be exposed to large short-term swings.

The U.S. Securities and Exchange Commission offers free, plain-language investor education at Investor.gov, including guidance on spotting fraud.
how to invest $100 as a beginner with a phone and growing savings

How to Invest $100 With Fractional Shares or a Robo-Advisor

Two beginner-friendly tools make small amounts easier to invest. Fractional shares let you buy a slice of a fund or company for an exact dollar amount, such as $100, instead of the full share price. A robo-advisor is an automated service that builds and manages a diversified portfolio for you based on a few questions about your goals.

Both can be a good way to learn how to invest $100 without picking investments yourself. With either one, compare fees first, make sure you understand how the account works, and start with an amount you are comfortable with.

What to Do After You Invest Your First $100

Once your first $100 is invested, the hardest step is behind you. Here is what to do next:

  • Do not panic if the balance drops. Short-term moves are normal, and checking every day makes them feel worse.
  • Keep investing on schedule. Put in the same amount every month, whatever the market does.
  • Increase gradually. Move from $100 toward larger amounts as your income allows, using the same steps.
  • Review once or twice a year. Check that your goals and investments still match, then leave it alone.

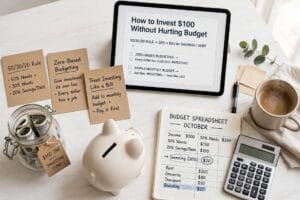
How to Invest $100 Without Hurting Your Budget

You do not need extra income to learn how to invest $100. You need a plan. Here is how it fits with popular budgeting methods:

  • 50/30/20 rule. Investing belongs in the 20% savings and debt category. See our guide to the 50/30/20 rule.
  • Zero-based budgeting. Give your investment its own line, so every dollar has a job.
  • Simple monthly budget. Add a line called “investing” and treat it like a bill. For the full picture, read our guide on how to budget.
how to invest $100 as a beginner with a phone and growing savings

Common Mistakes When Learning How to Invest $100

These mistakes are easy to avoid once you understand how to invest $100 the simple way:

  • Waiting for the perfect moment. Time in the market usually matters more than timing the market.
  • Putting all $100 into one stock. A single company is much riskier than a diversified fund.
  • Ignoring fees. Always check the expense ratio and any account fees.
  • Investing money you need soon. Keep short-term money in savings.
  • Checking your balance every day. Frequent checking often leads to emotional decisions.
  • Stopping after one bad month. Consistency is what builds results.

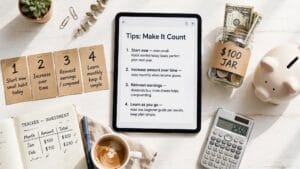
Tips for How to Invest $100 and Make It Count

  • Start now, even small. A habit started today beats a perfect plan started next year.
  • Increase the amount over time. Raise your monthly investment when your income grows.
  • Reinvest your earnings. Letting dividends buy more shares helps compounding.
  • Learn as you go. Read one beginner guide a month, and keep your plan simple.
how to invest $100 as a beginner with a phone and growing savings

Frequently Asked Questions About How to Invest $100

What is the best way to invest $100?

For many beginners, the best way to approach how to invest $100 is a low-cost, diversified index fund or ETF, bought through a brokerage account and repeated every month. The best choice depends on your goals, time frame, and comfort with risk.

Can I invest $100 with no experience?

Yes. A broad index fund requires no stock-picking skill, and many brokers offer simple tools for beginners. Start small, learn as you go, and avoid investments you do not understand.

Should I invest $100 or save it?

It depends on the goal. Money you need within a few years usually belongs in savings. Money for long-term goals such as retirement can be invested, as long as you have emergency savings first.

How much can $100 grow in a year?

There is no guaranteed number, because returns change every year and can be negative. Over long periods, the amount you add regularly usually matters more than the first $100.

Can I invest $100 a month?

Yes. Investing $100 every month is a common strategy. Setting up an automatic transfer makes it easier to stay consistent.

Do I need a lot of money to start investing?

No. Many brokers have no account minimum, and fractional shares let you invest small amounts. The most important part is to start with an amount you can keep up.

Final Thoughts

Knowing how to invest $100 is really about starting small and staying consistent. Make sure your basics are covered, open an account, choose a diversified low-cost fund, and set up an automatic monthly investment. The first $100 is only the beginning. The habit is what builds results over many years.

Ready to see what steady investing could look like? Try our free Investment Growth Calculator to estimate how your monthly contributions could grow, and read our guide on how to start investing with little money for the next steps.

This article is for educational purposes only and is not financial or investment advice. All investing involves risk, including the possible loss of money, and past performance does not guarantee future results. Consider speaking with a qualified professional about your specific situation.
How to Calculate Your Net Worth: A Simple Step-by-Step Guide

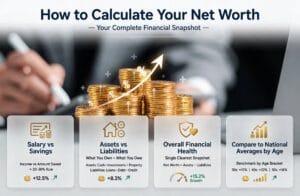
Knowing how to calculate your net worth gives you the single clearest snapshot of your overall financial health — more useful than your salary, your savings account balance, or any one number in isolation. This guide walks through exactly how to calculate it, what counts as an asset versus a liability, and how your number compares to national averages by age.

What Is Net Worth, Exactly?

Net worth is simply what you own minus what you owe. It’s a snapshot, not a judgment — a single number that captures your entire financial position at one point in time, regardless of your income level. Someone with a high salary but heavy debt can have a lower net worth than someone with a modest income but consistent saving habits.

How to Calculate Your Net Worth: The Basic Formula

Total Assets − Total Liabilities = Net Worth

That’s the entire formula. The complexity comes from accurately identifying everything you own and owe — which is exactly what the rest of this guide covers.

how to calculate your net worth guide

Step 1: List Every Asset You Own

An asset is anything of value that you own. Common categories include:

Cash and Cash Equivalents

  • Checking and savings account balances
  • Cash on hand
  • Money market accounts

Investments

  • Retirement accounts (401k, IRA, pension value)
  • Brokerage account balances
  • Stocks, bonds, and mutual funds held outside retirement accounts
  • Cryptocurrency holdings

Property

  • Current market value of your home (not what you paid for it)
  • Other real estate you own
  • Vehicle value (use current resale value, not purchase price)

Other Valuable Assets

  • Business ownership value, if applicable
  • Valuable collectibles, jewelry, or equipment (only include significant items)

A common mistake when learning how to calculate your net worth is using original purchase prices instead of current market value — especially for homes, vehicles, and investments. Always use what the item is worth today.

how to calculate your net worth guide

Step 2: List Every Liability You Owe

A liability is any debt or financial obligation. This includes:

  • Mortgage balance — remaining amount owed, not the original loan amount
  • Car loans — remaining balance
  • Credit card balances — current outstanding amounts
  • Student loans — remaining balance
  • Personal loans
  • Any other debt — medical debt, family loans, buy-now-pay-later balances

Be thorough here — forgetting even one liability inflates your net worth artificially, giving you a falsely optimistic picture of your finances.

how to calculate your net worth guide

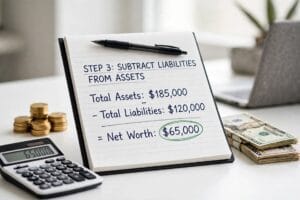
Step 3: Subtract Liabilities From Assets

Once you’ve totaled both lists, subtract your total liabilities from your total assets. For example:

  • Total Assets: $185,000
  • Total Liabilities: $120,000
  • Net Worth: $65,000

Want to skip the manual math? Our free Net Worth Tracker lets you plug in your numbers and calculates your net worth instantly, with the breakdown organized for you.

how to calculate your net worth guide

Is a Negative Net Worth Normal?

Yes — and it’s more common than most people realize, especially for younger adults with student loans or a recent mortgage. A negative net worth simply means your liabilities currently exceed your assets. It’s a starting point to build from, not a permanent condition, and many people move from negative to positive net worth over just a few years of consistent saving and debt paydown.

Average Net Worth by Age: How Do You Compare?

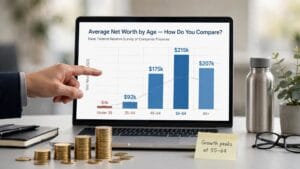
While your personal circumstances matter more than any national average, it can be useful context to see how net worth typically trends over a lifetime, based on data from the Federal Reserve’s Survey of Consumer Finances:

  • Under 35: Often near zero or negative, due to student loans and early career earning years
  • 35-44: Typically starts turning positive as income grows and debt gets paid down
  • 45-54: Usually shows the fastest growth period, as peak earning years combine with continued investment growth
  • 55-64: Often near its highest point, close to retirement
  • 65 and older: May plateau or decline slightly as retirement withdrawals begin

For the most current figures, the Federal Reserve’s Survey of Consumer Finances publishes detailed net worth data by age group every three years.

how to calculate your net worth guide

How Often Should You Calculate Your Net Worth?

Checking monthly is often too frequent — asset values like investments and home prices fluctuate constantly, and short-term swings can be discouraging without reflecting real progress. Most financial experts recommend calculating your net worth quarterly or twice a year, which is frequent enough to track meaningful trends without obsessing over normal market noise.

Why Tracking Net Worth Matters More Than Tracking Income

Income measures how much money flows through your hands, but net worth measures how much of it you’ve actually kept and grown. Someone earning a modest salary but consistently saving and investing can build significant net worth over time, while a high earner with heavy spending and debt may see little to no growth despite a bigger paycheck.

Tracking net worth regularly also reveals the real impact of financial decisions — paying off debt, building an emergency fund, or increasing retirement contributions — in a way that a bank balance alone never shows.

how to calculate your net worth guide

How to Improve Your Net Worth Over Time

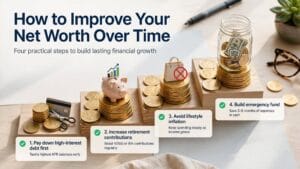
  • Pay down high-interest debt first. Every dollar paid off directly increases net worth by reducing liabilities.
  • Increase retirement contributions. Consistent investing compounds over decades, growing the asset side of the equation.
  • Avoid lifestyle inflation. As income grows, directing raises toward savings and debt payoff rather than increased spending accelerates net worth growth significantly.
  • Build an emergency fund. This prevents new debt from unexpected expenses, protecting your net worth from sudden drops. Our Emergency Fund Calculator can help you set a target.

how to calculate your net worth guide

Common Mistakes When Calculating Net Worth

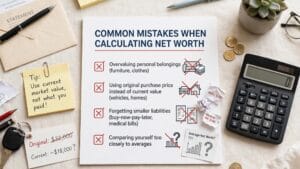
  • Overvaluing personal belongings. Furniture, clothes, and everyday items generally shouldn’t be included — they hold little resale value and clutter the calculation.
  • Using original purchase price instead of current value. This is especially common with vehicles and homes, which change value significantly over time.
  • Forgetting smaller liabilities. Buy-now-pay-later balances, medical bills, or small personal loans are often overlooked but still count.
  • Comparing yourself too closely to averages. Your own trend over time matters far more than how you stack up against a national statistic.

how to calculate your net worth guide

Final Thoughts

Now that you know how to calculate your net worth, make it a recurring habit rather than a one-time exercise. Tracking it quarterly or twice a year gives you a clear, honest picture of whether your financial decisions are actually moving you forward — regardless of what your income or spending habits look like month to month.

Ready to calculate yours? Try our free Net Worth Tracker and get your full breakdown in seconds — no sign-up required.

How to Evaluate Online Information Before You Trust It

The internet makes it possible to find an answer to almost any question within seconds. Yet speed does not guarantee accuracy. Search results can mix carefully researched reporting with outdated pages, unsupported opinions, advertising, and material created primarily to attract attention. Developing a reliable method for evaluating online information helps readers make better decisions without requiring specialist knowledge.

Start With the Source

The first step is to identify who is responsible for the information. A government department, university, professional association, established newsroom, or named subject-matter expert may provide useful context, although no category is automatically correct. Check whether the author is identified and whether the organisation explains its purpose, funding, or editorial standards.

Anonymous material deserves additional scrutiny, particularly when it makes strong claims about health, finance, politics, or public safety. A credible source should make it possible to understand the writer’s expertise and the basis for the argument. If ownership details are difficult to find, readers should treat that absence as relevant evidence rather than a minor inconvenience.

Examine the Evidence

Reliable articles generally distinguish between established findings, interpretation, and speculation. They may cite research papers, official statistics, interviews, court records, or other primary documents. References do not guarantee that a claim is sound, but they give readers a path for checking it.

Pay attention to whether the evidence actually supports the conclusion. A study involving a small group may not justify a sweeping claim about an entire population. Likewise, a personal story can illustrate an experience without proving that the same outcome is common. Good analysis explains limitations instead of presenting every result as definitive.

Links and labels can also reveal the status of a page. A placeholder link like test may signal that a document is unfinished, being used for demonstration, or awaiting a final reference. Recognising these clues prevents readers from treating an incomplete resource as polished evidence.

Check Dates and Context

Information can become misleading when it is separated from the time in which it was produced. Laws change, scientific understanding develops, prices fluctuate, and public statements may be corrected. Look for a publication date and, when available, an update history. An undated page should not automatically be dismissed, but its relevance is harder to judge.

Context matters just as much as timing. A statistic may describe one region, age group, or period while being presented as if it applied everywhere. Read beyond the headline, inspect the surrounding paragraphs, and note the definitions used. Numbers without a denominator, comparison point, or explanation can create a distorted impression even when they are technically accurate.

Compare Independent Accounts

Comparing several sources is useful when they are genuinely independent. Five pages repeating the same press release do not provide five separate confirmations. Try to locate the original report or statement, then compare it with reporting from organisations that use different methods and have different editorial perspectives.

Disagreement is not necessarily evidence that all sources are equally unreliable. It may reflect different data, definitions, or standards of interpretation. A careful reader asks what each account can establish, what remains uncertain, and whether the disagreement concerns facts or conclusions.

Recognise Persuasive Techniques

Online content often competes for attention through emotional language, dramatic images, and urgent appeals. These features do not prove that a claim is false, but they can encourage people to react before assessing it. Be cautious when a page pressures readers to share immediately, dismisses all criticism, or presents complex issues as having only one obvious explanation.

Before passing information along, pause and summarise the central claim in neutral language. Then ask what evidence would change your mind and whether the source addresses reasonable objections. This habit supports better judgment, reduces the spread of errors, and makes online discussion more constructive.