
To create a sinking fund, pick a specific expense you know is coming, divide its cost by the number of months you have to save, and move that amount into a separate account every month. That is the whole idea. A sinking fund turns a big, stressful bill into a small, predictable monthly habit.
In this guide you will learn how to create a sinking fund in seven simple steps, how to calculate the right monthly amount, where to keep the money, and how to fit sinking funds into your budget. You will also see a full example with real dollar amounts.
What Is a Sinking Fund?
A sinking fund is money you set aside in small, regular amounts for a specific expense you can predict, such as car repairs, holiday gifts, annual insurance, or a vacation. When the bill arrives, the money is already there, so you do not need a credit card or your emergency savings.
If you are new to the idea, start with our guide on what is a sinking fund, then come back here to learn how to create a sinking fund of your own.
Before You Start: Sinking Fund vs Emergency Fund
These two funds sound similar, but they do different jobs. An emergency fund is for surprises, such as a job loss or a sudden medical bill. A sinking fund is for costs you can see coming. Keeping them separate protects both goals, and knowing the difference is the first step in how to create a sinking fund that lasts. Our comparison of sinking fund vs emergency fund explains the difference in detail.
How to Create a Sinking Fund in 7 Steps
Follow these steps in order. Most people finish the setup in less than an hour.
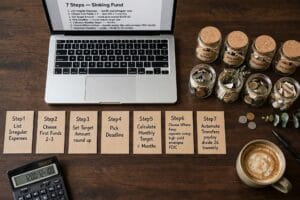
Step 1: List Your Irregular Expenses
Look through the last 12 months of bank and card statements and find expenses that did not happen every month. Common examples are car repairs, annual insurance premiums, holiday gifts, medical copays, vehicle registration, and travel.
This step shows you the costs that usually break a budget, because they are easy to forget until the bill arrives. It is the foundation of how to create a sinking fund that fits your life.
Step 2: Choose Your First Sinking Funds
You do not need ten funds on day one. The easiest way to learn how to create a sinking fund is to start with two or three that would hurt the most if they arrived unprepared. If you need ideas, see our list of sinking fund categories to find the ones that fit your life.
Step 3: Set a Target Amount for Each Fund
Estimate what each expense will cost. Use last year’s bills as a guide, and round up slightly. A reasonable estimate is better than waiting for a perfect number, and it keeps how to create a sinking fund simple.
Step 4: Pick a Deadline
Decide when you will need the money. A holiday fund has a clear date, while a car repair fund can simply run all year. The number of months until your deadline is what you divide by in the next step.
Step 5: Calculate Your Monthly Contribution
Use this simple formula to create a sinking fund plan for any goal:
Monthly contribution = Target amount ÷ Number of months
For example, if you want $1,200 for car repairs over 12 months, you save $100 each month. If you want $600 for holiday gifts and the holidays are 10 months away, you save $60 each month.
Step 6: Choose Where to Keep the Money
Where you keep the money matters as much as how to create a sinking fund on paper. Keep sinking funds separate from your everyday checking account, so the money is harder to spend by accident. Popular options include:
- A separate savings account. Many banks let you open extra accounts or create named savings buckets inside one account.
- A high-yield savings account. Interest rates change often, so compare current rates before you choose.
- Cash envelopes. This works for small, short-term funds, such as gifts or personal spending.
- A budgeting app with funds or goals. Some apps let you assign money to categories without opening new accounts.
If you use a bank, check that it is insured. You can confirm coverage on the FDIC website.
Step 7: Automate Your Transfers
Set up an automatic transfer for each fund on payday. Automation is the part of how to create a sinking fund that makes it stick, and it is the single biggest reason sinking funds work, because you never have to remember or decide each month. If you are paid every two weeks, divide the yearly total by 26 to get the amount per paycheck.
Sinking Fund Example: How the Numbers Work
Here is how to create a sinking fund plan with five funds. These amounts are examples, so replace them with your own estimates:
| Sinking Fund | Yearly Goal | Monthly Contribution |
|---|---|---|
| Car maintenance and repairs | $1,200 | $100 |
| Holiday gifts | $600 | $50 |
| Annual insurance premium | $960 | $80 |
| Vacation | $1,800 | $150 |
| Medical and dental costs | $600 | $50 |
| Total | $5,160 | $430 |
If you are paid biweekly, the same $5,160 divided by 26 paychecks is about $198 per paycheck. If $430 a month feels like too much, start with the two funds that matter most, such as car repairs and insurance, which come to $180 a month. You can add more funds later as your budget allows.
How to Fit Sinking Funds Into Your Budget
Knowing how to create a sinking fund is only half the job, because it also needs a place in your budget. Here is how it fits with popular methods:
- 50/30/20 rule. Sinking fund contributions belong in the 20% savings and debt category. See our guide to the 50/30/20 rule for the full breakdown.
- Zero-based budgeting. Give each sinking fund its own line, so every dollar has a job.
- Simple monthly budget. Add one line called “sinking funds” and split it between your funds.
For a full overview of budgeting methods, read our guide on how to budget.
Calculate Your Monthly Amount Faster
You can do the math by hand, but a calculator saves time when you have several funds. Try our free Sinking Fund Planner to turn your goals and deadlines into monthly amounts in seconds.
How to Create a Sinking Fund on a Tight Budget
Most people cannot fund everything at once, and that is perfectly normal. If money is tight, here is how to create a sinking fund step by step without stress:
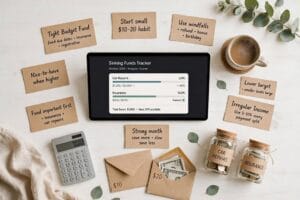
- Fund the expenses with fixed due dates first. Insurance and registration cannot be moved.
- Start with a small amount. Even $10 or $20 a month per fund builds the habit.
- Use windfalls. A tax refund, bonus, or birthday money can give a fund a head start.
- Lower the target. A smaller goal you can reach beats a large goal you give up on.
How to Create a Sinking Fund With an Irregular Income
If your pay changes from month to month, you can still learn how to create a sinking fund that works. Instead of a fixed amount, use a percentage of every payment you receive, such as 5% to 10%, and split it between your funds. In a strong month you save more, and in a slow month you save less.
Fund your most important categories first, such as insurance and car repairs, and add the nice-to-have funds when income is higher. For more ideas, see our guide on how to budget with an irregular income.
How to Create a Sinking Fund in a Spreadsheet
A simple spreadsheet is a free way to track everything. Create one row for each fund and add these columns:
- Fund name: for example, car repairs or holiday gifts.
- Goal amount: the total you want to save.
- Deadline: the month you will need the money.
- Monthly contribution: goal divided by the number of months.
- Current balance: what you have saved so far.
- Percent complete: current balance divided by goal.
Update the balance once a month, and you will see your progress at a glance. This takes about five minutes and keeps you motivated.
How Long Does It Take to Create a Sinking Fund?
You can set up a sinking fund in an afternoon, and most people see their first goal reached within a few months. The setup takes less than an hour. Saving time depends on the goal: a $300 holiday fund can be ready in six months at $50 a month, while a $2,400 vacation fund takes a year at $200 a month.
What to Do When You Spend From a Sinking Fund
Spending from a sinking fund is the point, not a failure. When the bill comes, pay it from the fund, then reset the fund and start saving again. If an expense turns out to be bigger than planned, raise next year’s target.
If a fund is not spent, you can keep rolling it forward, or move leftover money to another goal, such as your emergency fund or a debt payment.
Common Mistakes When Learning How to Create a Sinking Fund
- Mixing it with your emergency fund. Money for planned costs and money for surprises should stay separate.
- Starting too many funds at once. Begin with two or three, then add more.
- Leaving money in checking. It blends into your spending money and disappears.
- Raiding one fund to cover another. If you do, repay it as soon as possible.
- Skipping the automation. Manual saving is easy to forget during a busy month.
Tips for How to Create a Sinking Fund That Lasts
- Name each fund clearly. A name like “Car repairs” is harder to raid than “Savings 2.”
- Review once a year. Update your targets when prices or plans change.
- Pay yourself first. Move the money on payday before you spend on wants.
- Keep the numbers simple. Round your contributions to the nearest $5 or $10.
Frequently Asked Questions About How to Create a Sinking Fund
How do I create a sinking fund?
The simplest approach to how to create a sinking fund is to list your irregular expenses, choose two or three to start with, set a target amount and deadline for each, divide the target by the number of months, and automate a monthly transfer into a separate account.
How much should I put in a sinking fund each month?
Divide the cost of the expense by the number of months until you need it. For example, $1,200 over 12 months is $100 per month.
Where should I keep my sinking fund?
Keep it in a separate account from your everyday checking, ideally an insured savings account or a named savings bucket. This makes it harder to spend by accident.
Can I have more than one sinking fund?
Yes. Many people have several, such as car repairs, gifts, insurance, and travel. Start with two or three and add more as your budget grows.
Should I build an emergency fund or a sinking fund first?
Many people start with a small emergency fund, then add sinking funds. If you have no cushion at all, even a few hundred dollars in an emergency fund helps protect your sinking funds from being raided.
What is the difference between a sinking fund and a savings account?
A savings account is where money is stored. A sinking fund is a savings plan for a specific expense. You can keep a sinking fund inside a savings account.
Final Thoughts
Learning how to create a sinking fund is one of the easiest ways to stop big bills from wrecking your budget. Start small, pick two or three funds, do the simple division, and let automation do the work. In a few months, you will notice that bills that once felt like emergencies are just normal expenses you already planned for.
Ready to put how to create a sinking fund into practice? Use our Sinking Fund Planner to calculate your monthly amounts, and read our list of sinking fund categories to choose your first funds.
This article is for educational purposes only and is not financial advice. Consider speaking with a qualified professional about your specific situation.