
The simple answer to how much to put in a sinking fund is this: divide the cost of the expense by the number of months you have until you need the money. If a $1,200 car repair budget needs to be ready in 12 months, you put in $100 a month. If you have only six months, it becomes $200 a month.
In this guide you will learn how much to put in a sinking fund for common expenses, how to convert the amount into weekly or biweekly savings, and what to do when the numbers do not fit your budget. You will also see real dollar examples you can copy.
The Simple Formula for How Much to Put in a Sinking Fund
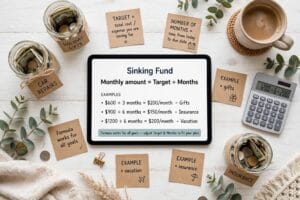
Every sinking fund uses the same formula, whether you are saving for gifts, insurance, or a vacation:
Monthly amount = Target amount ÷ Number of months
That is all you need to know how much to put in a sinking fund for any goal. The target amount is what the expense will cost, and the number of months is the time between today and the due date. If you are not sure what a sinking fund is yet, start with our guide on what is a sinking fund.
How to Find Your Target Amount
The formula is easy, but the target is where most people get stuck when deciding how much to put in a sinking fund. Use these three steps to find a realistic number:
- Look back 12 months. Check your bank and card statements for what you actually spent on the expense last year.
- Estimate honestly. If last year was unusually low or high, use a more typical figure.
- Add a small buffer. Prices rise, so adding 5% to 10% to your target protects you from coming up short.
A rough target you actually use is better than waiting for a perfect number. You can always adjust it later.
How Much to Put in a Sinking Fund: Examples by Category
Here is how much to put in a sinking fund for eight common expenses. These amounts are examples, so replace them with your own numbers:
| Sinking Fund | Yearly Goal | Monthly Amount |
|---|---|---|
| Car maintenance and repairs | $1,200 | $100 |
| Holiday gifts | $600 | $50 |
| Annual insurance premium | $960 | $80 |
| Vacation | $1,800 | $150 |
| Medical and dental costs | $600 | $50 |
| Home maintenance | $1,500 | $125 |
| Pet and vet care | $480 | $40 |
| Annual subscriptions | $240 | $20 |
| Total | $7,380 | $615 |
Most people do not need all eight funds at once. If you want ideas for which ones fit your life, see our list of sinking fund categories.
How Much to Put in a Sinking Fund Each Paycheck
If you are paid weekly, biweekly, or twice a month, you can convert the monthly amount into the amount per paycheck. Divide the yearly goal by the number of paychecks you receive in a year:
| Pay Schedule | Paychecks Per Year | Per Paycheck for $100 a Month | Per Paycheck for $615 a Month |
|---|---|---|---|
| Weekly | 52 | $23.08 | $141.92 |
| Biweekly | 26 | $46.15 | $283.85 |
| Twice a month | 24 | $50.00 | $307.50 |
| Monthly | 12 | $100.00 | $615.00 |
If you are paid biweekly, remember that you receive 26 paychecks a year, not 24. That means two months each year have three paychecks, which is a good chance to give your sinking funds an extra boost.
How Much to Put in a Sinking Fund Based on Your Income
If you are not sure where to start, a rough guideline is to set aside about 5% to 10% of your take-home pay for all sinking funds combined. This is only a starting point, not a rule, because your real costs depend on your car, home, family, and habits. Here is what that range looks like at different incomes:
| Monthly Take-Home Pay | 5% for Sinking Funds | 10% for Sinking Funds |
|---|---|---|
| $2,500 | $125 | $250 |
| $3,500 | $175 | $350 |
| $5,000 | $250 | $500 |
Use these numbers to check your plan, not to replace it. If your own list of expenses adds up to much more or less, trust your list.
How Much to Put in a Sinking Fund: A Worked Example
Let’s say you take home $4,000 a month and decide to set aside 7.5% for sinking funds, which is $300. Here is one way to split it:
| Sinking Fund | Monthly Amount |
|---|---|
| Car maintenance and repairs | $100 |
| Annual insurance premium | $80 |
| Holiday gifts | $50 |
| Vacation | $70 |
| Total | $300 |
This is a realistic example of how much to put in a sinking fund when your budget is limited. The fixed-date and high-risk expenses, such as insurance and car repairs, get the largest share, and the fun goals get what remains.
How Much to Put in a Sinking Fund With an Irregular Income
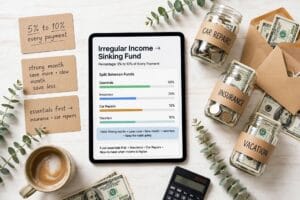
If your income changes every month, a fixed amount can be hard to keep. Instead, set aside a percentage of every payment you receive, such as 5% to 10%, and split it between your funds. In a strong month you save more, and in a slow month you save less, but the habit continues. Fund the essentials first, such as insurance and car repairs, and add the nice-to-have funds when income is higher.
How Often Should You Review Your Amounts?
Review your targets at least once a year, and again after any big change, such as a new car, a move, or a new family member. Prices change and your life changes, so the right answer to how much to put in a sinking fund today may be different next year. A quick ten-minute check is usually enough.
What If the Deadline Is Close?
Knowing how much to put in a sinking fund gets harder when a bill is close and you have not saved yet. The formula still works, but you divide by the months you have left, and you subtract what you already saved:
Monthly amount = (Target amount – Amount already saved) ÷ Months left
For example, suppose a $960 insurance bill is due in four months and you have not saved anything. You would put in $240 a month. If you have already saved $300, the formula becomes ($960 – $300) ÷ 4, which is $165 a month.
When the monthly amount is too high, you have three choices: lower the target, find extra money for a few months, or use a small part of your regular budget so you do not need a credit card.
What If You Cannot Afford the Full Amount?
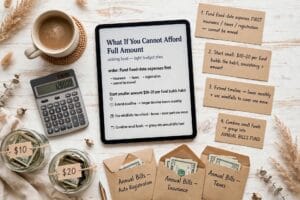
Most people cannot fund everything right away, and that is completely fine. When you are figuring out how much to put in a sinking fund on a tight budget, try this order:
- Fund fixed-date expenses first. Insurance, taxes, and registration cannot be moved.
- Start with a smaller amount. Even $10 or $20 a month per fund builds the habit.
- Extend the deadline. A longer timeline lowers the monthly amount for goals that can wait.
- Use windfalls. A tax refund or bonus can cover part of a fund in one move.
- Combine small funds. If you have several tiny funds, group them into one “annual bills” fund.
Should You Add a Buffer?
A small buffer is a smart part of deciding how much to put in a sinking fund realistically. Prices tend to rise, and many expenses turn out a little higher than expected. Adding 5% to 10% to your target means you are less likely to come up short.
For example, if you expect holiday spending of $600, plan for $650 or $660. That adds only a few dollars a month, but it can save you from a last-minute shortfall.
Sinking Fund Amount vs Emergency Fund Amount
The amount for a sinking fund is based on specific known costs, while an emergency fund is usually based on a few months of essential living expenses. Keep the two separate, because mixing them makes it easy to spend your safety net on planned costs. Our guide on sinking fund vs emergency fund explains how they differ and how to build both.
How Sinking Funds Fit Into Your Budget
Your sinking fund total needs a home in your budget. Here is how it fits with popular methods:
- 50/30/20 rule. Sinking fund contributions belong in the 20% savings and debt category. See our guide to the 50/30/20 rule for details.
- Zero-based budgeting. Give each sinking fund its own line, so every dollar has a job. Our guide to zero-based budgeting shows how.
- Simple monthly budget. Add one line called “sinking funds” and split it between your funds. For the full picture, read our guide on how to budget.
Calculate Your Amount in Seconds
If you have several funds, the math can get tedious. Use our free Sinking Fund Planner to enter your goals and deadlines and see exactly how much to put in a sinking fund each month. The Consumer Financial Protection Bureau also offers free budgeting worksheets at consumerfinance.gov.
Common Mistakes When Deciding How Much to Put in a Sinking Fund
- Guessing without checking past spending. Your bank statements tell you what you really spend.
- Forgetting small annual costs. Subscriptions, registrations, and fees add up quickly.
- Setting targets too low. A very low target leaves you short when the bill arrives.
- Setting targets too high. An amount you cannot keep up will lead you to quit.
- Never updating the numbers. Review your targets once a year, because prices and plans change.
Tips for Getting the Amount Right
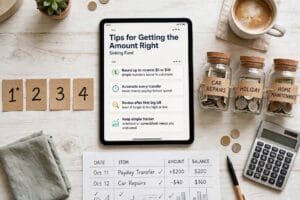
These simple habits make it easier to decide how much to put in a sinking fund and keep to it:
- Round up to the nearest $5 or $10. Simple numbers are easier to automate and remember.
- Automate every transfer. Move the money on payday before you can spend it.
- Review after your first big bill. You will quickly learn whether your target was too high or too low.
- Keep a simple tracker. A notebook or spreadsheet showing each fund’s balance keeps you motivated.
Frequently Asked Questions About How Much to Put in a Sinking Fund
How much should I put in a sinking fund each month?
Divide the expense by the number of months until you need it. For example, $1,200 over 12 months is $100 per month.
How much should I put in a sinking fund for a car?
Many people budget between $50 and $150 a month for car maintenance and repairs, depending on the age and cost of the car. Use last year’s repair and maintenance bills as your guide.
What percentage of my income should go to sinking funds?
A common starting point is 5% to 10% of take-home pay for all sinking funds combined. Your real number depends on your expenses, so build the total from your own list.
How many sinking funds should I have?
Start with two or three and add more as your budget allows. Most people end up with between three and eight funds.
What if I cannot save the full amount each month?
Save a smaller amount, extend the deadline, or lower the target. A small, steady contribution is better than skipping the fund entirely.
Do I stop saving once a fund reaches its goal?
You can pause, or you can keep going if the expense repeats. After you pay the bill, reset the fund and start saving for next year.
Final Thoughts
Figuring out how much to put in a sinking fund is simpler than it seems. Find the target, divide it by the months you have, add a small buffer, and automate the transfer. If the total feels too big, start with your two most important funds and build from there.
Ready to build your plan? Use our Sinking Fund Planner to calculate your monthly amounts, and follow our step-by-step guide on how to create a sinking fund to set everything up.
This article is for educational purposes only and is not financial advice. Consider speaking with a qualified professional about your specific situation.